

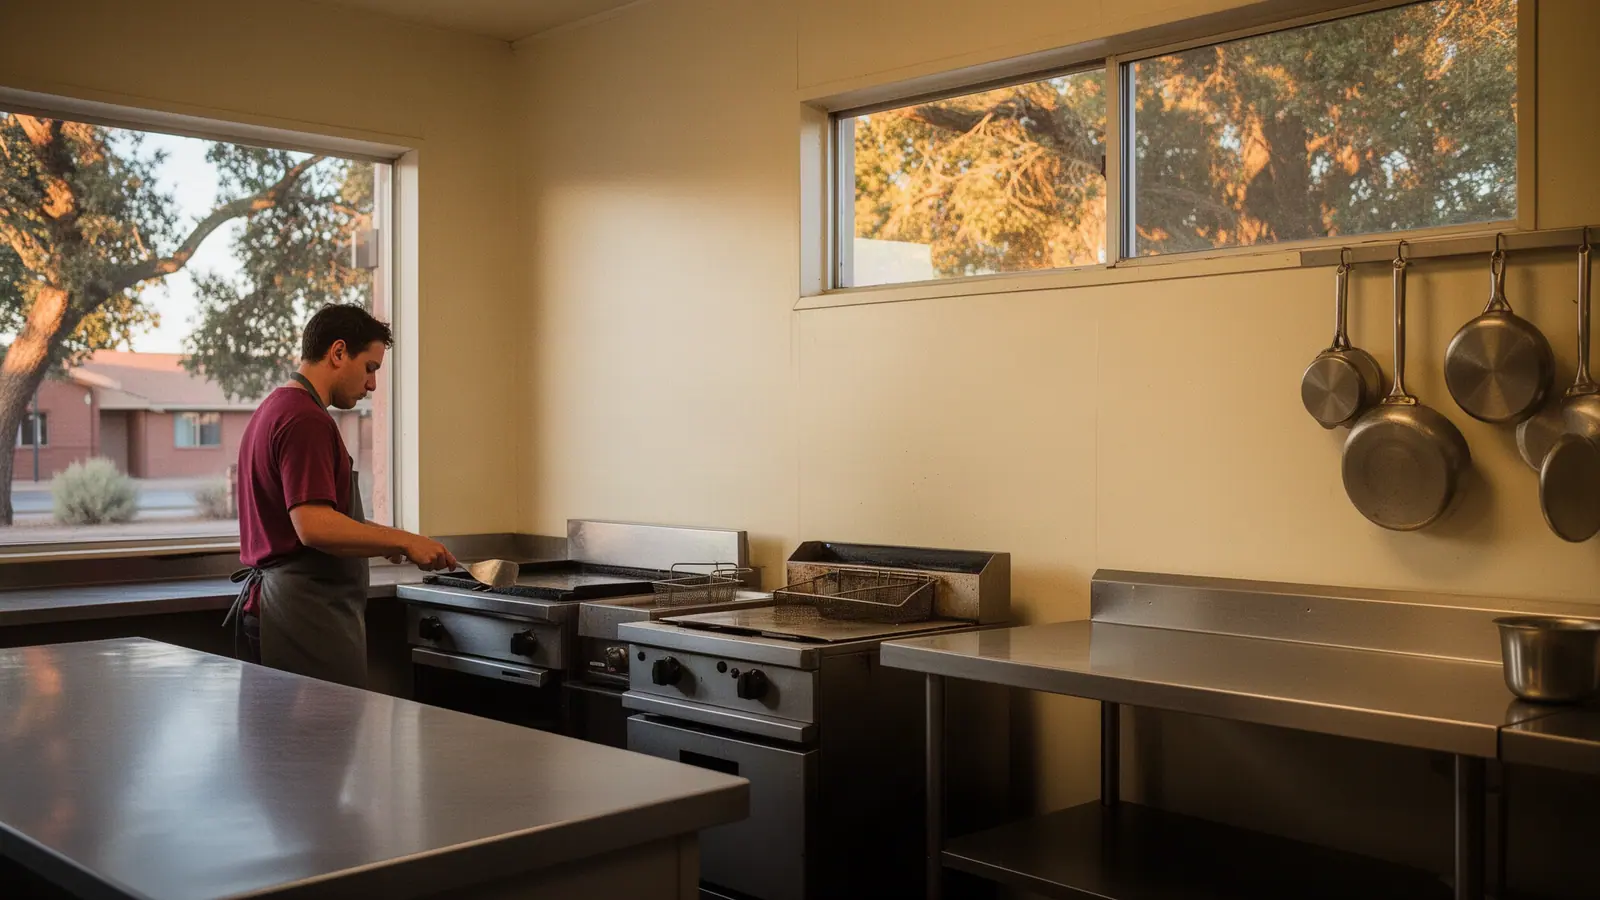
Small Business Loans in Mountain Home, ID for Contractors and Local Shops
Ledgeford Business Loans turns a Mountain Home, ID small business loan need into one request that independent funding partners review and decide on: working capital, equipment financing, a line of credit, a term loan, inventory financing or a merchant cash advance.
- Six funding types compared
- Phone or a short online form
Local shops and contractors use this route. County Business Patterns counted 256 employer establishments with fewer than five employees among the 477 in Elmore County, ID for 2023.
How a Mountain Home, ID request moves from the call to a partner
Four stages, from naming the cost to reading an offer.
Name the cost
Say what the money pays for, the amount on the quote or invoice, and when it is due.
Talk it over
Ledgeford asks a few questions about the business and which funding type matches the cost.
Partner review
A funding partner reads the request, asks for bank statements or returns, and checks the numbers.
Read the offer
If a partner makes an offer, compare its total cost and schedule before you sign anything.
The other funding types a Mountain Home, ID business can ask about
Each page explains what the funding pays for, how it is paid back and what a partner reviews.
Working Capital Loans
Cash for the stretch between paying a crew or a kitchen staff and collecting from the job, the builder or the card processor.
Typical uses
- Cover payroll between deposits
Equipment Financing
A loan or a lease for a flat-top, a walk-in cooler, a skid steer, a mower deck or an alignment rack, paid over the machine's working years.
Typical uses
- Replace a fryer, cooler or freezer
Business Lines of Credit
A limit you draw on for food orders, drywall mud or parts and pay down when deposits land, with interest only on the drawn part.
Typical uses
- Keep a line for food and supply orders
Business Term Loans
One lump sum and a fixed schedule for buying an operating business, movable equipment or furnishings for a second location.
Typical uses
- Buy a restaurant or center that is for sale
Inventory Financing
Money to stock shelves, parts bins or a supply room before the sales that will pay for the goods come in.
Typical uses
- Stock a store ahead of a large order
Merchant Cash Advances
A sale of future card receipts, not a loan: a provider collects a fixed share of card sales until an agreed total is reached.
Typical uses
- Draw on card sales at a diner
Name the grill, the payroll date or the business you want to buy
Call (208) 445-0233 to talk it through, or send the short request form. Independent partners review the request and decide.
What banks look for in an Elmore County, ID landscaping company business plan
A bank or another funding partner reading a landscaping plan wants to see how the money turns into revenue, not a mission statement. Put four things near the top: the jobs or maintenance contracts already signed, the equipment list with what each machine is worth, the payroll the crew draws every pay period, and the exact use of the money being requested.
Elmore County, ID landscaping outfits are small by the Census count. County Business Patterns found 11 employer establishments in landscaping services (NAICS 561730) in 2023, and 8 of them had fewer than five employees. Their 33 paid employees drew $1,207,000 in annual payroll, about $36,576 each (our arithmetic). A partner reading a plan from a company that size can check whether one lost contract would leave the payroll uncovered.
- Contracts and recurring accounts, with start dates and monthly value
- Mowers, spray rigs and trucks owned or financed, with balances still owed
- Twelve months of bank deposits, so the plan’s revenue figure can be checked
- The use of funds in one line: a second crew, a skid steer, or wages until a builder pays
A plan that names the cost, and the cash that will cover the payment, can spare the owner a round of follow-up questions.
Business loans in Idaho for Elmore County, ID drywall and flooring contractors
Drywall hangers, tapers, painters and flooring installers sit in one Census group, building finishing contractors (NAICS 2383). Elmore County, ID had 13 of them with paid staff in 2023, and 11 of those 13, or 84.6%, had fewer than five employees (County Business Patterns). A finishing crew that small may front materials and wages and wait for the general contractor’s draw.
Nonemployer Statistics counted 27 building finishing businesses in the county with no paid employees in 2024: owner-operators who hang, tape or lay floor themselves. Their funding questions look different, because there is no payroll to carry, only materials and tools.
New homes set the pace of finishing work. For 2025, the Building Permits Survey reports 164 new privately owned housing units authorized in Elmore County, ID. Those are housing-unit counts, not a funding offer for property work. For a crew waiting on those payments, a business line of credit for mud, tape and flooring stock, or a working capital loan for wages match the gap; a five-year term loan does not.
How business loans work for Mountain Home, ID auto repair shops and quick-service restaurants
A business loan is a fixed sum paid back on a schedule with interest. A partner looks at how the business earns money and whether that income covers the new payment. For an auto repair shop, the income is labor and parts billed per ticket; for a quick-service restaurant, it is a stream of card and cash sales every day.
The scale differs too. Elmore County, ID auto repair and maintenance shops numbered 11 with paid staff in 2023 and employed 47 people, about 4.3 per shop (our arithmetic on County Business Patterns). Limited-service restaurants, the code that covers quick-service restaurants and other counter-order places, numbered 22 and employed 455; their payroll averaged about $28,189 a month per restaurant (our arithmetic on the $7,442,000 annual total).
That difference shapes the request. A shop that needs a lift or a scan tool fits equipment financing, where the machine secures the debt. A counter-service kitchen with a payroll that large may look at a line of credit or a working capital loan sized to a few pay periods, and an advance on card sales is a third option, one that is not a loan at all.
The industries page gives county counts for auto repair shops and both kinds of restaurant, and the Mountain Home, ID page reads the same data for landscapers and builders.
Types of business loans Mountain Home, ID drywall and flooring contractors can compare, by what each one pays for
Six funding types line up with the costs a finishing or flooring contractor carries, and each one is paid back differently. The list below matches each to a cost on the job, so the request names the right one from the first call.
- Working capital loan: wages for tapers and installers while a builder’s draw is pending
- Business line of credit: drywall, mud, underlayment and plank flooring, drawn as jobs start
- Equipment financing: a texture sprayer, a lift, a floor sander or an equipment trailer
- Business term loan: buying out a retiring partner’s share, or another crew’s business
- Inventory financing: a pallet order of flooring bought ahead at a lower unit price
- Merchant cash advance: can be a poor fit for invoice-based billing, because providers collect from card sales
The funding types page sets the six side by side with what each costs to carry and what a partner reviews. A contractor whose income arrives in draws should compare the line of credit and the working capital loan first. Shops and stores have their own retail page, and crews their own construction page.
How to qualify for a business loan as an Elmore County, ID quick-service restaurant
There is no single bar a counter-service restaurant clears; each funding partner sets its own requirements. What a partner reviews is consistent enough to prepare for: how long the restaurant has been open, monthly card and cash sales, bank balances, existing debts and leases, and the owner’s credit.
- Pull the last several months of bank statements and the card processor’s monthly summaries
- List every loan, equipment lease and advance with its payment and the date it ends
- Most recent annual business return and a current-year profit and loss statement
- Write the use of the money: a fryer bank, a walk-in repair, or two payrolls during movable-equipment setup
Payroll weighs heavily in this trade. With 455 paid employees across 22 limited-service restaurants in Elmore County, ID (County Business Patterns 2023), payroll is worth explaining on the request, with the headcount and the pay schedule. Calling (208) 445-0233 before gathering everything is fine; the desk can talk through which papers matter for the funding type in question.
What happens after a request goes out is laid out on the how it works page, and the blog walks through a 13-week cash forecast.
Line of credit or term loan: how child care centers in Elmore County, ID choose
A child care center needs two kinds of money: steady money for wages and food between tuition payments, and one-time money for freestanding classroom furniture or a van. A line of credit suits the first, because the center draws and pays down as tuition arrives. A term loan suits the second, because the cost is known and the payment can be planned.
Elmore County, ID child day care employers numbered 13 in 2023, with 83 paid employees and payroll of about $12,968 a month per center on average (our arithmetic on County Business Patterns). Nonemployer Statistics separately counted 23 child care services businesses (NAICS 62441) with no paid employees in 2024.
Illustration only, invented figures: a center borrows $28,000 for new cubbies, cots and indoor soft-play pieces over 36 months at an annual rate of 11.5%. That works out to $923.33 per month; the 36 installments come to $33,239.88 in all, and $5,239.88 of that is interest. The same center might keep a line open for wages; if one payroll is $5,400 and tuition lags 30 days, 2 or 3 biweekly payrolls fall inside the wait, so $10,800 to $16,200. A center with both figures in hand can start on the application page.
Questions before a Mountain Home, ID funding call
Short answers; a call to the desk covers the rest.
Call Ledgeford(208) 445-0233Does sending the Ledgeford request form count as a credit application?
No. The form passes your contact details, time in business, revenue and the amount you have in mind to Ledgeford, and it is not a credit application. A funding partner that reviews the request may check business or personal credit during its own review, and it can explain what kind of check it runs before it does.
Can a business outside the Mountain Home, ID city limits send a request?
Yes. The desk sits in Mountain Home, ID, but the request is about the business and its costs, not its street. The same phone line and request form are available throughout the rest of Elmore County, ID. The exceptions are trucking companies and agricultural operations, which Ledgeford does not pass to partners.
What happens to a request once it has been sent?
Ledgeford looks at what the money pays for and matches it to a funding type. It then goes to one or more independent funding partners. Each partner reviews the business, asks for the papers it needs and decides on its own whether to make an offer and on what terms.
Send the request with the cost it has to cover
The form asks for a name, phone, email, company name, time in business, annual revenue and the amount requested. Sending it is not a credit application; a funding partner may check credit later, during its own review.
- Six funding types compared
- Phone or a short online form
- Elmore County, ID
See our Privacy Policy, Terms and SMS Terms.
Pages that pair with this one for a Mountain Home, ID business
About Ledgeford
About Ledgeford Business Loans in Mountain Home, ID: where a small business request starts, who reviews it and how the steps run.
The contact page
Contact Ledgeford Business Loans in Mountain Home, ID: call (208) 445-0233, use the request form, or see the office address and questions to ask.